
“Europe resembles an overgrown teenager who has outgrown their clothes” – this was the comparison used by Lithuanian President Dalia Grybauskaitė in an interview with the European news portal EurActiv. She believes that to overcome the current eurozone crisis and cope with future global challenges, the European Union (EU) must revise its collective policy, striving for greater monetary and fiscal coordination. [..] To collectively manage global challenges, Europe requires deeper integration. To integrate in terms of economy, one must also integrate in the finance and services sectors, but there is still a long way to go before that. However, without a common market, it is very difficult to coordinate economic, monetary, and fiscal policy. “A currency without a common monetary and fiscal policy is an artificial construct. Without coordination, it is impossible to speak with one voice and make lightning-fast decisions,” the Lithuanian President said.
LETA, 25 May 2010
Europe's strength lies in its diversity – the distinct skills of each nation together create a wonderful cocktail. One of the nicest European cocktails is Kir Royale, a classic blend of champagne lightened with Crème de Cassis blackcurrant liqueur. The best blackcurrants for Cassis liqueurs come from Dijon in France and form the basis of Crème de Cassis de Dijon. Kir Royale is a wonderful aperitif that precedes many important events, so it is truly no wonder that providence decreed that Cassis de Dijon itself should occupy an important place in the origins of the modern European Union's legal system.
Europe consists of sovereign states, each of which individually possesses far greater autonomous power than, for example, the states of the USA. Countries have distinct cultures, characters, needs, and languages; their laws are not merely different, but radically, systematically different – ranging from somewhere between English common law and the French Napoleonic Code. The beginning of the European Union – just a customs union for steel and coal, that is, an agreement not to impose import duties on two groups of goods in mutual trade – did not require any major harmonisation of laws. However, how should one proceed? How can one create a unified European system while maintaining, and not breaking, this diversity? How can French and English laws be combined? How can a unified Europe be achieved without destroying, but rather strengthening, the national? How can, for example, the standardisation of goods be achieved? Should German standards be imposed on everyone, or perhaps the French or English ones? In 1979, the European Court of Justice (ECJ) brilliantly resolved this complex task in the Cassis de Dijon case.
Every European country has its own laws and standards that determine what goods can be produced and how. German standards state that liqueur must contain at least 25% alcohol. French-produced blackcurrant liqueurs contain only 15–20% alcohol, so Germany banned their sale within German territory for failing to meet standards. The liqueur importer Rewe-Zentrale AG believed that the German government was hiding protectionism behind a mask of standards, thereby illegally protecting the German liqueur industry from foreign competition. This action, Rewe concluded, was in clear contradiction with one of the fundamental freedoms of the EU – the free movement of goods – and it initiated proceedings against the government agency Bundesmonopolverwaltung für Branntwein.
One of the few possible restrictions on the free movement of goods in European legislation is a potential threat to public health, so the German government chose to defend the ban on importing Crème de Cassis de Dijon, insisting that the poor German consumer, by buying this sub-standard French liqueur, could drink it too easily because they would not feel the liqueur's usual taste of alcohol. Excessive consumption, in turn, would cause a wave of alcoholism among naive German consumers – a threat to public health! The German subsidiary argument was that standard dumping must not be permitted.
The 1979 ruling of the European Court of Justice was brilliant, simple, and life-changing for Europe. The Court ruled that if a blackcurrant liqueur meets the standards of the member state where it is produced, it must be accepted as meeting standards in all other member states. With a single stroke of the pen, all standard and legislative disputes were ended. By recognising all laws and standards simultaneously, Europe was able to maintain diversity while being unified in that diversity. Now, the European Commission was left with the easiest task – simply issuing directives that set minimum standard levels to prevent extreme incompatibility.
Thanks to such flexible and inclusive legislation, the single European market was able to solidify and develop without centralisation, while allowing each national government to look after its own interests. Consequently, Europe was able to form a successful union and single market without creating a large federal government and by collecting in taxes only one percent of total GDP, or on average just 1/40th of national government spending.
In the financial sphere, diversity in unity in the pre-euro era was maintained by national currencies, which were tightly pegged to one another with fixed exchange rates – like the lat to the euro at present. Fixed rates provided the stability required for trade, but the status of a national currency allowed for occasional monetary policy intervention, regulating the amount of money in circulation by changing the rate against surrounding countries. Highly competitive countries, especially Germany, repeatedly revalued, or raised their rate, to curb their exports and thus the inflow of money and investment into an overheated economy; southern Europeans devalued, or lowered rates, to stimulate the receipt of new investments as a now cheaper country for production, while at the same time, the rate change promoted exports and increased the size of the local economy. More money in circulation flowed into the economy as increased corporate profits, higher wages, and ultimately, increased prosperity. Likewise, the state budget was supplemented and, measured relatively against wealth, state and private debt decreased.
On average, a European country could maintain a fixed rate for about ten years until a decline in competitiveness caused by one type of bubble or another was corrected by lowering the rate and, with it, prices. This allowed for simultaneous wage increases and price reductions, creating sustainable growth in wealth and economic development over many decades, lifting many European countries from poverty into the ranks of the world's wealthiest nations and allowing for the development of industry across Europe, not just in the skilled North.
Rarely performed, a currency devaluation as a solution to competitiveness problems is a very effective economic stimulus tool with no negative consequences (unless the country has issued loans in foreign currencies). However, politicians and officials do not like devaluations very much, because then they have to admit to their voters that the country was managed worse in the previous period than its neighbours, whose currency remains strong. Therefore, they have always tried to avoid changing the rate until the very last moment or have attempted to invent reputation-saving methods. For example, the French government repeatedly did not unilaterally devalue the franc against the German mark, but negotiated and/or forced Germany to perform a simultaneous revaluation of the mark's rate, telling the public that France was not devaluing the franc, but rather a “European currency rate adjustment” was taking place. Among other things, the thought was attractive that, by introducing a single euro, politicians would never again have to suffer the embarrassment of a poor Finnish Prime Minister who, on the very last night before the mark's devaluation, promised the nation on television that “a strong mark is the basis of a stable Finnish economy.” Furthermore, the creation of the euro was an opportunity for Mitterrand, Kohl, and others to accomplish something big, grandiose, and historic, immortalising themselves in the annals of history. Therefore, politicians chose not to listen to the opinions of leading European and American finance professors [1. Jonung, Lars and Drea Eoin, The Euro: It can’t happen. It’s a bad idea. It won’t last. US Economists on Euro, 1989-2002, European Commission Working Paper, 2009.], that the euro in its intended form is a bad idea; they chose to ignore an open letter from a hundred leading German economists to the government requesting the postponement of the single currency's introduction until Europe was ready for it, and the euro was born.
As a result, a production and trade policy based in principle on Cassis de Dijon, individualised and centred in national states, combined in Europe with a hard currency policy dictated by the European Central Bank based in Frankfurt. In practice, this meant that countries that did not notice or were unable to prevent a decline in economic competitiveness, or were unable to organise an industrial policy suited to their price level, entered a downward spiral where ever-larger private sector borrowings led to an ever-greater amount of euros in circulation, which further raised prices, because of which competitiveness further decreased. In the good old days, a bubble would burst, the currency would devalue, and the economy would start its next growth cycle. A single currency can no longer be devalued. Therefore, it is impossible to resolve a crisis by lowering prices with printed money to be invested in the implementation of employment-promoting infrastructure projects and investments in science and education that would lift the country to a new level of competitiveness. With the single euro, the national governments that find themselves in crisis can only reduce their budgets, thereby doubling the severity of the crisis (as in Latvia).
If a Latvian city, say, Ludza, gets into financial difficulties, it receives support from the municipal equalisation fund. If a US state gets into trouble, it is helped by the federal government, which collects in taxes and spends evenly across the country around 17% of America's GDP. Unfortunately, the European financial system is currently not ready for a unified fiscal policy. Brussels collects a relatively small part of the total economy in taxes, so it does not have much money to invest in stimulating the economies of member states that have fallen into crisis. It can provide large-scale aid only by borrowing and lending money at interest to crisis-hit countries; however, such “aid” only increases the debt burden of the crisis-hit member state, further slowing down rather than promoting the economy.
Consequently, national states not only no longer have the possibility to regulate the amount of money in their economies, have no opportunity to control financial capital flows, and have no instruments for overcoming a crisis through investments in infrastructure and development, but they are forced to pour oil on the fire by reducing state budget expenditures during a crisis. On average, every euro that the state spends less reduces the gross domestic product by the same amount. With a decrease in turnover, tax revenues fall, and the country enters a downward spiral with massive unemployment – as in the Baltics, Ireland, and Spain. As countries try to save by reducing investments in infrastructure, their attractiveness in the eyes of industrial investors falls, which leads to an even worse economic situation. Therefore, the euro is disadvantageous to absolutely everyone, perhaps with the exception of banks that can endlessly borrow euros on the market and provide euro loans (creating bubbles of infinite size), and tourists who do not have to carry various currencies in their pockets.
To be able to meaningfully support a member state during a crisis under the conditions of a single currency, a unified European government and the level of centrally collected taxes seen in the USA are required. A single currency requires a single state. Then one could implement, for example, a unified industrial policy aimed at the industrialisation of lagging regions, as Germany, China, or even the former USSR did. If a large and unified Europe had its own government, then it could provide large-scale aid (not loans!) to everyone affected by difficulties. However, not only the lack of funds stands in the way of such an economic system. To carry out such aid, high legislative compatibility, the power to redistribute money over donor regions to collect a sufficient amount of money there, and power over recipient regions to ensure the reasonable, coordinated spending of money for the realisation of a unified European common economic goal are practically required. In Europe, it will be difficult to create this. At the moment, the European Union is governed by a small group of appointed, not elected, officials who are engaged in legislative harmonisation, not pan-European development. We do not have a strong European Parliament. There are no strong pan-European elections.
European politicians are, of course, populist, bad, etc., however, a state managed by uncontrolled officials is even worse – as everyone who lived in the USSR well remembers or sees in China. Democracy, with all its flaws, is the best possible form of government. Therefore, the first step in creating a centralised Europe should be strengthening the European Parliament, which could be followed by an increase in the European budget and a reduction in the power of local governments. I think Europe is not ready for that. Many countries, first and foremost Great Britain, keenly protect their sovereignty. The English voter is convinced that European officials would manage Albion worse than local politicians and does not want to transfer power to Europe. Even the Lisbon Treaty, which was relatively modest in terms of sovereignty changes, encountered huge difficulties in many countries, let alone more ambitious projects.
Therefore, it is expected that Europe will not soon be a unified, unitary state. It will not have a large, unified government with social planners who would have sufficient funds available to care for true equalisation of living standards between Romania, Latvia, and France – the current European structural funds are clearly insufficient and, moreover, aimed more at solving ecological problems, supporting treatment plants and similar structures, but not directly at the creation of new factories and employment. Europe will not soon have, for example, a centralised hospital budget that receives money regardless of whether or not the country is in crisis, thus serving as an automatic stabiliser. The European system is based on the light, decentralised Cassis de Dijon principle, at the centre of which is the national state, but this principle is in clear contradiction with the centralisation of the monetary system.
Therefore, since the introduction of the euro, Europe has experienced the lowest growth rate in post-war history, effectively stagnation, and has now entered a huge crisis. The way out of it will be either a significantly more centralised Europe, which will be similar to the United States and where the economic system will be adapted to the monetary system, or a return to the pre-euro era of national currencies, i.e., adapting the monetary system to the economic and political system, or some combination of both of these principles. Such major, fundamental changes will happen neither easily nor painlessly.
The European Union is currently supporting Latvia to a huge extent with the help of loans, yet it is obvious that funds so far have been granted more to prevent Latvia's crisis from spreading to the rest of Europe, rather than to practically promote our economic development or prevent unemployment – because Europe's economic-political structure is not ready for a supportive development policy.
After the introduction of the euro, there was euphoria in many parts of the world, and ideas were circulating that regional currencies should be created around Japan, in the Persian Gulf countries, and in Latin America. All these plans, seeing the failure of the euro, have been abandoned. It is also in Latvia's national interests to create its own monetary system adapted to the reality of today's Europe, not the dreams of central banks and Brussels officials. European Union countries in the post-war period, when they were at a similar stage of development as Latvia is now, can serve as an example to us of how to become wealthy by implementing an aggressive, national-interest-aligned monetary policy aimed at industrialisation, debt write-offs, and competitiveness improvements. Then, when Europe has transformed and adapted itself to a single currency, Latvia must, of course, join the euro, but only on the condition that we are sufficiently developed and ready for the fierce competition in the single currency market. Of course, if Europe does not cope with the necessary reforms and continues to stagnate, we should remain outside the euro zone altogether. Such a national policy will allow us to easily overtake Estonia, which is currently making a grave mistake by introducing the euro prematurely.
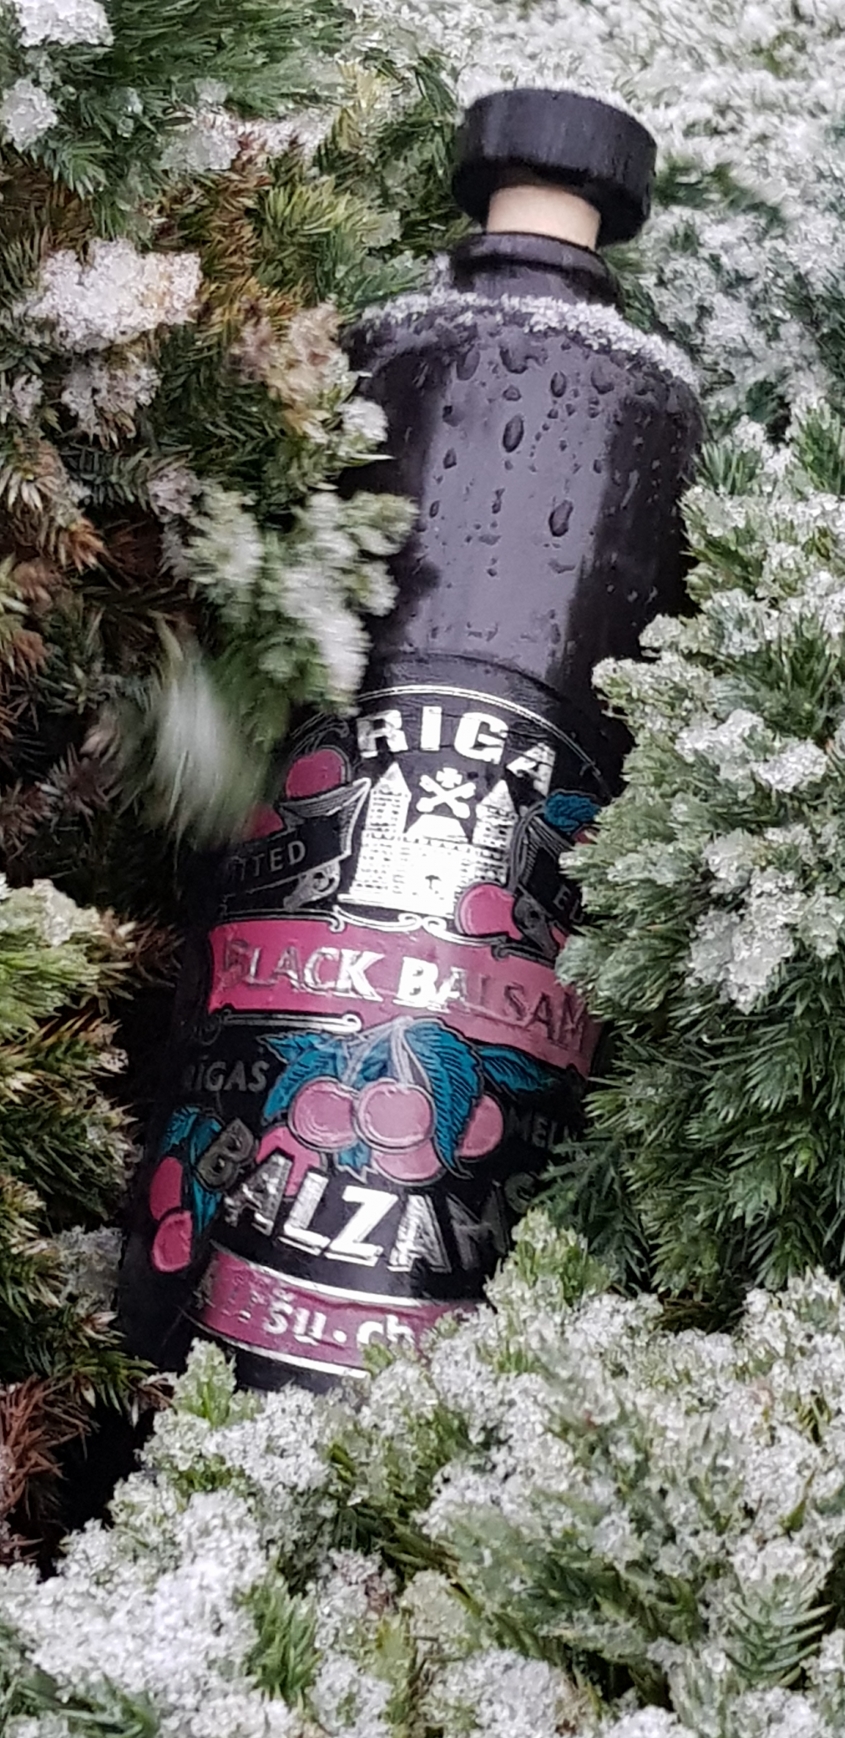
The European Union is a great opportunity for Latvia to develop and join the West. Only, the joining must be done correctly. We must ensure that we, with our own strength, with funds earned by our own industry, can buy both Dom Perignon and Crème de Cassis de Dijon, to celebrate a Latvia that has reached European wealth in a nice local restaurant. Although – Rīgas Melnais balzams mixed into Rīgas šampanietis will also do.
Article first published in the July 2010 issue of the magazine Rīgas Laiks